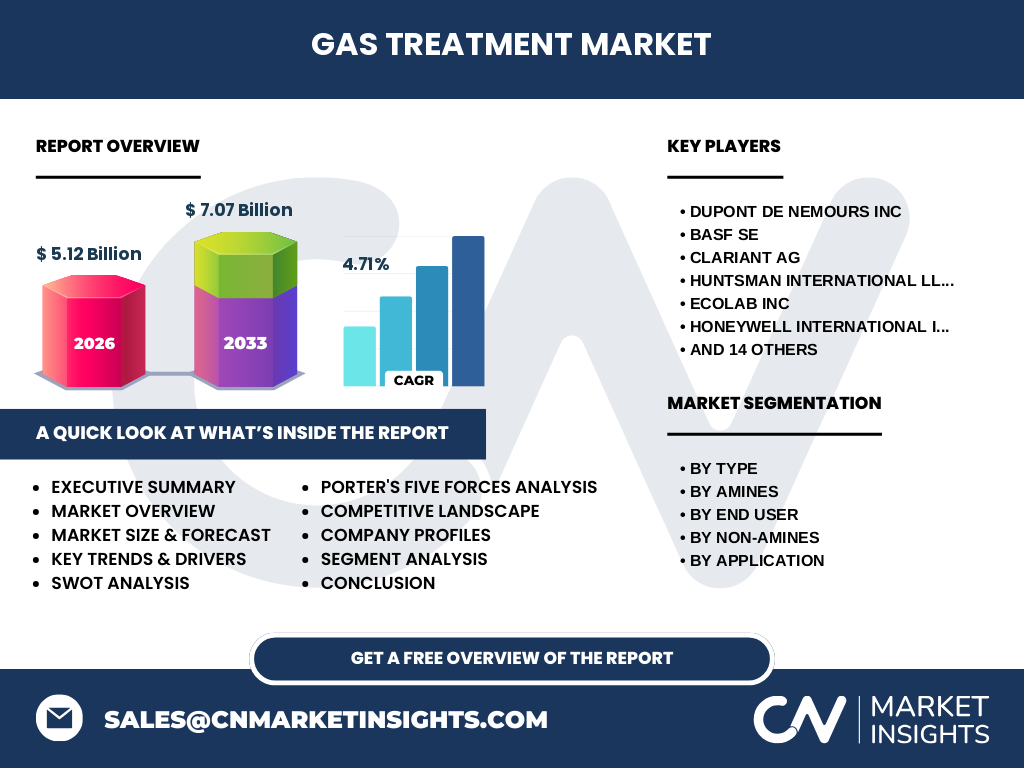
Market overview of the Gas Treatment Market
Our analysis indicates that the Gas Treatment Market is valued at 5.12 Billion in 2026, driven by critical requirements in upstream and downstream energy sectors. The scope encompasses the removal of acid gases, moisture, and contaminants using advanced chemical and physical solvents to meet stringent pipeline specifications and environmental compliance standards.
What are the core drivers, restraints, and opportunities in the Gas Treatment Market?
The Gas Treatment Market industry trends highlight strict environmental regulations by bodies like the EPA as a primary driver. Restraints involve high capital expenditures for amine regeneration units. However, rising natural gas demand creates massive opportunities for specialized chemical formulations provided by industry leaders such as BASF SE and Exxon Mobil Corporation.
Emerging growth patterns and technological shifts
Our research shows a definitive pivot toward high-efficiency blended amines and sustainable solvent-based treatments. Technological innovation focuses on reducing energy penalties during solvent regeneration. Companies like Shell plc and DuPont de Nemours Inc are spearheading proprietary formulations that significantly lower operational carbon footprints across major processing facilities.
How did the COVID-19 pandemic impact industry recovery trajectories?
The pandemic caused temporary supply chain disruptions and deferred capital projects within the Gas Treatment Market. Based on our research, the recovery trajectory has been robust, accelerated by post-pandemic energy demand surges and mandatory infrastructure upgrades implemented across critical midstream assets operated by firms such as Chevron Corporation.
Competitive Benchmarking and Market Concentration
The competitive landscape features a mix of multinational chemical giants and integrated energy enterprises. Market concentration is moderate to high, with key players like Dow, Clariant AG, and Huntsman International LLC leveraging proprietary intellectual property in molecular sieves and physical absorbents to secure long-term supply contracts with major refiners.
Executive summary of key findings
Our comprehensive Gas Treatment Market analysis reveals a highly resilient sector projected to reach 7.07 Billion by 2033. Strategic growth is anchored in stringent sulfur-recovery mandates and expanding liquefied natural gas infrastructure. Market participants must prioritize bio-based solvents and digital monitoring to maintain competitive differentiation.
Market forecast from 2027 to 2033
The data suggests steady expansion, projecting the Gas Treatment Market market size to climb from 2027 through 2033 at a steady CAGR of 4.71%. This trajectory reflects sustained capital investments in natural gas processing plants and stricter global sulfur cap regulations enforced across maritime and industrial applications.
Segmentation analysis across types and end-users
Market segmentation divides the industry by type into Amines (Primary, Secondary, Tertiary, Blended) and Non-Amines (Solvent-Based, Physical Absorbents, Molecular Sieves). End-user categories focus on Power Plants and Refineries, while application segments target Acid Gas Removal and Dehydration for pipeline transport.
Geographic distribution and regional performance
Regional performance varies based on local hydrocarbon reserves and environmental policy strictness. North America and the Middle East dominate consumption due to extensive shale gas extraction and massive refinery complexes. Meanwhile, Asia-Pacific exhibits the fastest growth rate, fueled by rapid industrialization and shifting energy mixes emphasizing cleaner-burning natural gas.
In-depth regional review of key growth zones
North America maintains leadership in the Gas Treatment Market driven by stringent environmental oversight from agencies like the EPA and vast Permian Basin midstream buildouts. Simultaneously, the Middle East leverages massive capital investments in sour gas processing, utilizing advanced technologies from providers like Axens SA and TotalEnergies SE.
Strategic positioning of leading companies
Key market participants deploy distinct strategies to capture share. BASF SE and Solvay SA focus on advanced chemical solvent portfolios, while Honeywell International Inc emphasizes integrated molecular sieve technologies. These players maintain dominance through continuous R&D investment and localized technical service networks supporting major energy operators.
Porter's Five Forces competitive intensity assessment
Our analysis indicates moderate-to-high supplier power due to proprietary chemical formulations protected by patents. Buyer power remains constrained by the critical nature of gas sweetening agents. Threat of substitution is low in large-scale operations, though regulatory pressures continuously challenge incumbents to develop greener, lower-toxicity solvent alternatives.
SWOT analysis of the industry ecosystem
Strengths include robust intellectual property and mission-critical end-use applications. Weaknesses involve high energy requirements for solvent regeneration. Opportunities lie in expanding LNG liquefaction trains globally. Threats stem from volatile raw material petrochemical costs and tightening workplace safety regulations governing amine exposure limits worldwide.
Value chain analysis from raw materials to end-users
The value chain initiates with upstream petrochemical feedstock sourcing, followed by specialized chemical synthesis conducted by market leaders such as Arkema SA and Evonik Industries AG. Formulations flow through specialized distributors to refiners and power generators who utilize them for sweetening sour gas streams prior to final distribution.
Investment insights and high-potential focus areas
Strategic recommendations highlight blended amine formulations and regenerable physical absorbents as high-yield investment targets. Investors should prioritize partnerships with technology providers offering modular gas sweetening units capable of servicing remote shale plays and offshore platforms where footprint and weight constraints dictate operational viability.
Conclusion and key strategic takeaways
In summary, the Gas Treatment Market represents a stable, high-value sector underpinned by environmental compliance and rising energy demand. Companies that successfully commercialize energy-efficient, low-foaming amine blends and sustainable molecular sieves will capture outsized market share through the forecast period ending in 2033.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining official trade registry data, primary stakeholder interviews with refinery chemical engineers, and secondary macroeconomic indicators. This multi-tiered approach ensures high fidelity in market sizing, revenue estimations, and growth trajectory validation across all regional sub-segments.
Scope of the report and coverage parameters
This report covers global consumption, revenue projections, and volume metrics for the Gas Treatment Market from historical baselines through 2033. Excluded from this scope are localized, unpermitted domestic treating operations and non-commercial pilot-stage solvent technologies lacking verifiable industrial deployment records across major economic zones.
Recent developments, partnerships, and strategic expansions
Recent industry momentum features strategic joint ventures aimed at decarbonizing natural gas processing. Firms like Eastman Chemical Company and Clariant AG have announced capacity expansions for specialized desiccants and catalysts, responding directly to surging export terminal demands across Gulf Coast and European maritime trade hubs.